The Integration Debt Problem: Why Technology Investments Compound Cost Instead of Capability
When organizations acquire systems without governing how those systems connect, they build a hidden integration debt that quietly taxes every operation the technology was supposed to improve.
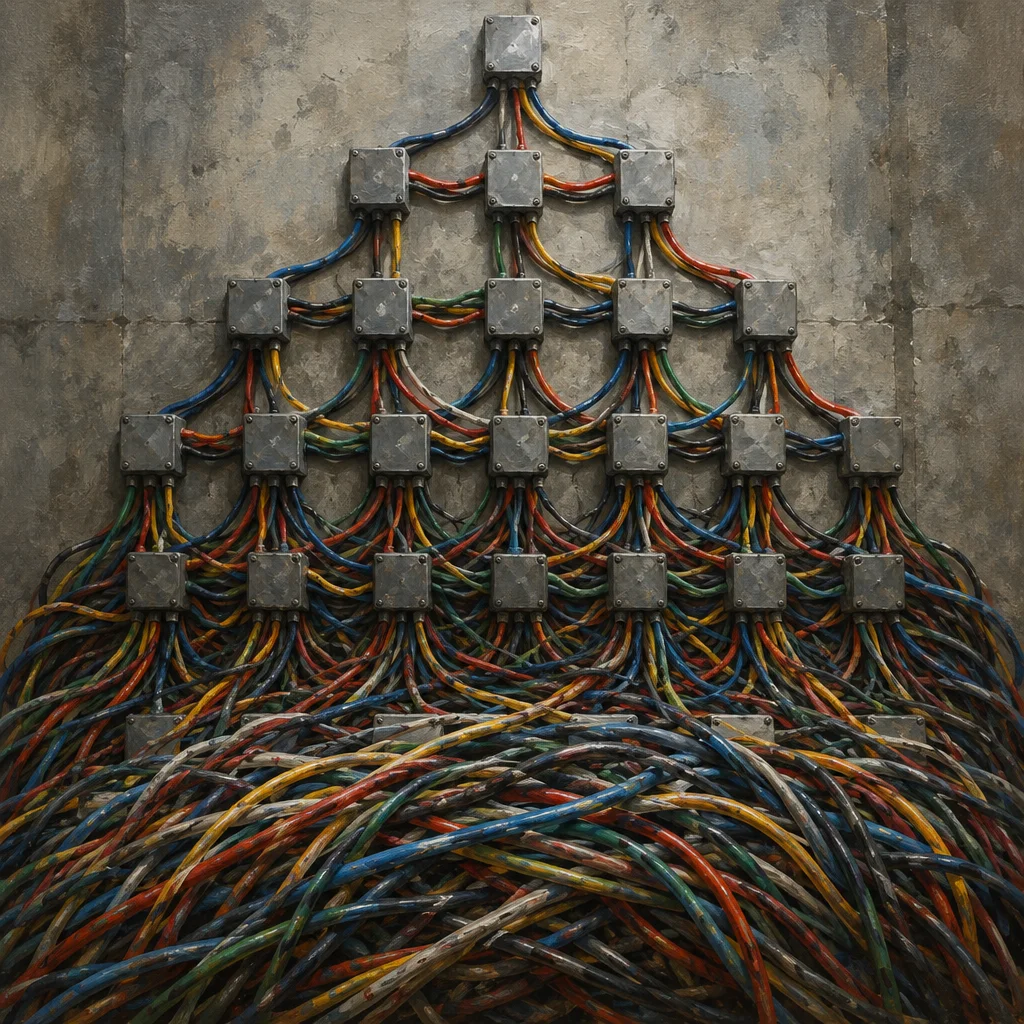
Most technology investment decisions are evaluated at the point of acquisition. A director reviews a capability gap, a vendor presents a solution, a business case moves through approval, and a contract is signed. What that process rarely examines is the question of connection: how this new system will interact with the fifteen other systems already running, who will own those interactions, and what the cumulative cost of unmanaged connections will look like eighteen months from now.
The result is a pattern that appears in organizations across industries and sizes. Each individual technology decision looks rational. The collective architecture does not.
What Integration Debt Actually Is
Integration debt is the accumulated cost of point-to-point connections, manual workarounds, and duplicated data that organizations build when they treat each system acquisition as a standalone event rather than a component decision within a broader architecture.
In practical terms, it shows up in recognizable ways. Data that exists in three systems and matches in none of them. Reports that require an analyst to reconcile exports before a director can trust the numbers. Processes that are nominally automated but require a human to move a file between two systems that were never connected. Onboarding workflows that involve entering the same information into four separate platforms because no one designed a shared record.
None of these problems are dramatic. Each one is manageable in isolation. But collectively they represent a structural tax on every operation that touches the affected systems, and that tax compounds as the organization grows, as headcount increases, and as additional systems are added to a foundation that was never designed to receive them.
Why the Acquisition Process Misses It
Standard technology acquisition processes are optimized to evaluate a system on its own merits. Does it solve the problem it was purchased to solve? Does it meet security requirements? Does it fall within budget? These are legitimate questions, and answering them well is genuinely difficult.
What those questions do not surface is architectural fitness: whether the system can exchange data cleanly with existing platforms, whether the vendor's integration approach is standards-based or proprietary, whether the total cost of ownership includes the connections the system will require, and whether any team in the organization has clear ownership of those connections once the implementation project closes.
Implementation projects make this worse. A typical implementation is scoped to get the new system functional. Integration work that falls outside that scope gets deferred, frequently indefinitely. The system goes live, the project closes, and the connections that were deferred become permanent workarounds that no future project is ever chartered to address.
The Ownership Gap at the Center of the Problem
Integration debt persists partly because it is nobody's problem in a way that generates sustained organizational attention. Individual systems have owners. The connections between systems typically do not.
When a data discrepancy appears between a CRM and a financial system, the CRM team points to the financial system and the financial team points to the CRM. When a workflow requires a manual step because two platforms were never connected, the team performing the manual step absorbs it as part of their operating cost. It rarely gets escalated because it is not dramatic enough to escalate, and it rarely gets fixed because no team has a charter that covers the space between the two systems.
This is not a technology failure. It is a governance design failure. Organizations that resolve it do so by creating explicit ownership of the integration layer, not as an IT project but as an ongoing operational responsibility with visibility at a leadership level.
What a Governance-Oriented Approach Looks Like
Directors who have managed this problem effectively tend to share a few structural habits worth considering.
First, they treat integration assessment as a standard component of any system acquisition, not an afterthought. Before a contract is signed, the acquisition review asks how the proposed system will connect to existing platforms, what that connection will cost to build and maintain, and who will own it. If those questions cannot be answered clearly, that uncertainty becomes a factor in the decision, not a detail to be resolved during implementation.
Second, they maintain a current-state map of how systems in their domain connect and where data flows. This does not need to be an elaborate technical document. Even a functional diagram reviewed quarterly gives leadership a basis for making connection decisions deliberately rather than by accumulation.
Third, they assign integration ownership to a role rather than a project. The question of who is accountable for the health of the connections between systems should have a named answer that survives any single implementation engagement. Where that accountability sits varies by organization, but the absence of it is almost always visible in the quality of the data leadership receives.
Fourth, they build integration cost into the total cost of ownership calculation for new systems. A platform that is inexpensive to license but expensive to connect, or one that requires proprietary middleware that creates vendor dependency, may carry a higher true cost than its acquisition price suggests.
The Strategic Consequence of Leaving This Unaddressed
Integration debt is worth executive attention not because the individual symptoms are catastrophic but because of where it degrades organizational capability over time.
Organizations carrying significant integration debt make decisions more slowly because data reconciliation takes longer. They scale less efficiently because every new headcount or workflow inherits the tax of the existing workarounds. They are harder to reorganize because the connections between systems often encode assumptions about how teams are structured that require significant effort to change. And they are more exposed during leadership transitions because the workarounds that hold the environment together frequently exist only in the operational knowledge of specific individuals.
Consider a hypothetical organization that has grown from two hundred to eight hundred employees over a decade, acquiring systems at each stage of growth without a governing integration architecture. By the time a new director steps into that environment, the integration debt is typically invisible until a significant operational event makes it visible: a reporting failure before a board meeting, a data migration that surfaces three years of inconsistencies, or a system retirement that reveals how many manual processes were quietly compensating for a connection that was never built.
The cost of addressing integration debt in that moment is substantially higher than the cost of governing it continuously would have been. That is the nature of compounding debt in any form.
A Starting Point for Directors Inheriting This Problem
For directors who suspect they are operating in an environment with significant integration debt but have not yet mapped it, the most productive first step is usually a structured conversation with the teams closest to the data. Ask where they spend time reconciling information between systems. Ask where manual steps exist in workflows that appear automated on paper. Ask which reports require preparation work before the numbers can be trusted.
Those answers will locate the integration debt more accurately than any system audit, and they will identify the connections that are most worth governing first. The goal is not to eliminate all technical complexity, which is neither realistic nor necessary, but to ensure that the connections between systems are deliberate, owned, and visible to leadership before they accumulate into a structural constraint on what the organization can do next.